
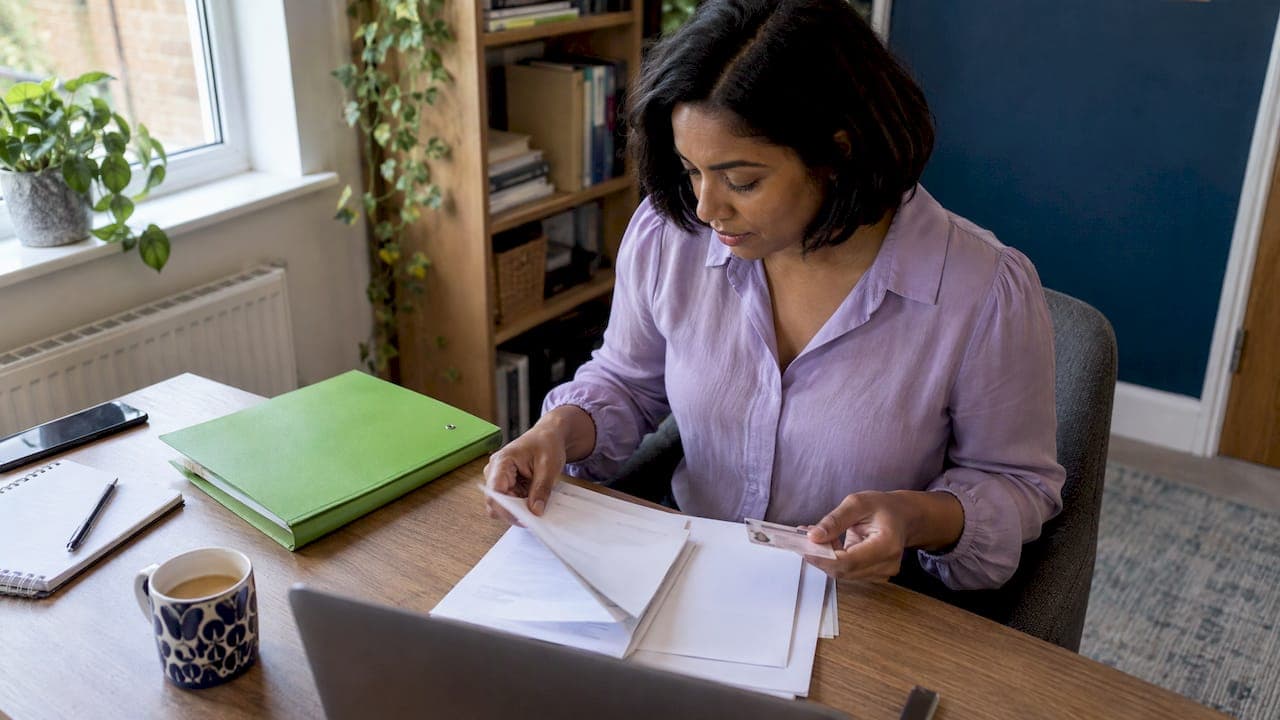
For most UK car leases you need four things: photo ID, proof of where you live, proof of what you earn and your driving licence details. Self-employed drivers and company directors add business paperwork. Funders can differ on the exact list, so treat this as the usual starting point and have it ready before you apply. A complete set of documents is the quickest way to get from enquiry to approval.
TL;DR
- Identity: a valid photo ID, usually a passport or photocard driving licence, plus your personal details.
- Address: proof of where you live now and, if you have moved recently, where you lived before. Bank statements and utility bills are the usual choices.
- Income: commonly recent payslips or bank statements, often covering the last three months. Self-employed applicants may be asked for more.
- Driving licence: you can share your record with a licence check code from GOV.UK, so a photocopy is rarely the whole story.
- Credit and affordability: the funder checks both, which is why the paperwork needs to match what you put on the application.
Table of Contents
- The core documents most funders ask for
- Proof of identity
- Proof of address
- Proof of income for a car lease
- Your driving licence and the DVLA check code
- Credit and affordability checks: how they shape the paperwork
- Extra documents for business leases
- Driving instructors and NHS staff
- A step-by-step way to get ready
- After approval: what you will sign and keep
- Our perspective
- Ready to start your lease?
- FAQ
- Sources
The core documents most funders ask for
A car lease is a contract hire agreement. A finance company owns the car and you pay a fixed monthly rental. Because it is a credit agreement, the funder must be satisfied about who you are, where you live and whether you can afford the payments. The paperwork exists to answer those three questions.
We publish our own overview of this in what documents you need to lease a car in the UK. The checklist below goes further and explains why each item is asked for.
| Document | What it proves | Typical examples |
|---|---|---|
| Photo ID | You are who you say you are | Passport, photocard driving licence |
| Proof of address | Where you live | Recent bank statement, utility bill, council tax bill |
| Proof of income | You can afford the rental | Payslips, bank statements, company accounts |
| Driving licence details | You are legally able to drive the car | Licence number and check code |
| Bank details | Where the Direct Debit comes from | Account number and sort code |
| Employment details | Stability of income | Employer name, job title, time in the role |
You will not always upload every item. Many applications start with an online form and the funder asks for specific documents only if its automated checks cannot confirm something. Having the full set to hand means a request does not stall the process.
Proof of identity
The funder needs to confirm your full name, date of birth and current address. Alongside the form, expect to be asked for photographic ID. A valid passport or a photocard driving licence covers this for most people.
A few practical points:
- The name on your ID should match the name on your application and bank account. If you have changed your name through marriage or deed poll, keep the supporting document close by.
- Use the same spelling of your address everywhere. Mismatches between the application, the electoral roll and your bank statements are a common reason for a manual review.
- If you recently arrived in the UK, your documents may look different. Our guide to expat car leasing in the UK covers what you need to qualify.
Proof of address
Funders usually want evidence that you live where you say you do. The most common choices are a recent bank statement, a utility bill or a council tax bill, dated within the last few months and showing your name and full address.
If you have lived at your address for under three years, be ready to give previous addresses too. Credit reference agencies look at your address history, and a gap or a typo can cause a mismatch that has nothing to do with your finances.
Two things to avoid: a bill in someone else's name (unless it is a joint account that includes you), and a screenshot that crops off the date or the address. Download the full PDF from your online banking or supplier instead.
Proof of income for a car lease
This is the document people worry about most, and it is also the most flexible. The affordability question is simple: after your usual outgoings, can you comfortably meet the monthly rental?
According to a UK guide on proof of income for car finance, recent payslips or bank statements are commonly requested, usually covering the last three months. The same source notes that some lenders may use Open Banking to assess affordability and verify income, and that limited-company owners may provide company accounts.
If you are employed
Have your last three payslips and the bank statements showing your wages arriving. If your pay varies because of overtime, shift allowances or bonuses, the statements often tell the clearer story, because they show what actually reaches your account.
It also helps to know your employer's name and address, your job title and how long you have been in the role. A recent job change is not a barrier on its own, but the funder may want to see a contract or offer letter alongside your first payslips.
If you are self-employed
Self-employed applicants are usually asked for more evidence, because income is not fixed. Typical items include:
- Bank statements, commonly the last three to six months, for the account your trading income goes into.
- Your SA302 tax calculations and tax year overviews from HMRC, if you have filed a Self Assessment return.
- Business or personal accounts prepared by an accountant, where you have them.
- Your Unique Taxpayer Reference and the date your business started trading.
Not every funder asks for all of these. If you are new to self-employment, say so up front. It is better to explain a short trading history than to leave the funder to find it.
If you do not have payslips
A payslip is not always necessary. The same UK guide says lenders may accept bank statements as proof of income, including for self-employed applicants and people claiming benefits, and that some may offer Open Banking, with your permission, to verify income and spending. Affordability checks still apply, so statements showing steady income and no pattern of missed payments make the case for you.
Your driving licence and the DVLA check code
A lease lets you drive the car, so the funder and the insurer need to know your licence status. In Great Britain you can view and share your driving record online through GOV.UK. The service lets you generate a licence check code that lets someone else see your driving licence information for a limited time.
Before you start, get these ready:
- Your driving licence number.
- Your National Insurance number.
- The postcode on your licence.
Check your record before you apply. If the address on your licence is out of date, update it with the DVLA first, so it matches your application. Endorsements and points are shown on the record, so know what is on yours before the funder sees it.
You will also need insurance in place before you collect the car. Most funders require fully comprehensive cover, and your insurer will ask for your licence details too.
Credit and affordability checks: how they shape the paperwork
Documents are one half of an approval. The other half is the credit search. The funder looks at your credit file for payment history, existing borrowing and any defaults, then compares your income against your outgoings.
Two habits make this smoother:
- Check your own credit report first. Fix errors, make sure you are on the electoral roll at your current address and close accounts you no longer use.
- Avoid scattershot applications. Several hard searches in a short time can look like financial stress. A broker can often tell you which funder is likely to suit your profile before anything is searched.
Our guide to car lease credit checks explains what applicants should expect, and how to pass a lease eligibility check walks through the steps in order. If your credit file is thin or damaged, a guarantor with soft checks may be an option, in which case your guarantor will need to supply ID, address and income evidence too.
If you are also planning to apply for a mortgage, note that a lease is a monthly commitment that lenders may count. We cover that in how a car lease can affect mortgage borrowing.
Extra documents for business leases
Business car leasing asks for company details as well as personal ones. Expect to be asked for:
- Company name, registered address and company registration number (limited companies).
- Date of incorporation or start of trading.
- Details of directors or partners, including ID and home addresses. For smaller companies, a personal guarantee from a director is often part of the picture.
- Recent business bank statements and, for established companies, filed accounts.
- VAT registration number, if you are VAT registered.
Sole traders are normally assessed on personal documents, as above, plus proof of trading. If you are comparing structures, our business car leasing page explains the options, and van leasing follows the same document pattern for commercial vehicles.
Driving instructors and NHS staff
The core list does not change for these groups, since the funder still needs ID, address, income and licence details. What changes is the evidence of income and the type of car.

Driving instructors are usually self-employed, so expect the self-employed paperwork above: bank statements showing lesson income and, where available, tax calculations. You may also be asked about your Approved Driving Instructor status. Instructors need a car that suits tuition, so it is worth telling the adviser at the start.
NHS staff can usually evidence income with payslips, which are straightforward, since the employer is stable and the pay is regular. Bring your NHS payslips and employment details. Shift allowances and bank work can vary month to month, so bank statements help show the full picture.
We offer specialist routes for both groups from our home page, where you can start an enquiry.
A step-by-step way to get ready
- Collect ID. Passport or photocard driving licence, in date.
- Download statements. Three months of bank statements as full PDFs, for the account your income reaches.
- Gather income evidence. Three payslips, or the self-employed set.
- Generate your licence check code. Have your licence number, National Insurance number and postcode ready.
- Check your credit file. Look for errors, and confirm you are on the electoral roll.
- Line up insurance quotes. You will need cover before delivery.
- Tell your adviser anything unusual. Recent moves, job changes, gaps in employment or previous credit problems are easier to handle when explained early.
The wider journey, from enquiry to handover, is in our car leasing process step by step, and the final stage is covered in the lease car delivery process.
After approval: what you will sign and keep
Once the funder approves you, you will receive the agreement and the pre-contract information, which sets out the rental, the term, the mileage allowance and the charges. Read it before you sign, in particular the excess mileage rate and the condition standards the car must meet when it returns.
Keep a copy of everything. When the car is delivered, you will not receive the V5C registration document, since the funder is the registered keeper, but you will have your agreement and handover paperwork.

Condition matters at the end of the lease too. A car that is cleaned properly and regularly is easier to keep within fair wear and tear standards, and a car pre wash guide can help you choose a routine that protects the paintwork between washes.
Our perspective
Most delayed lease applications we see are not rejected for affordability. They stall because a document is missing, out of date or does not match the form.
That is why we work the other way round. As a family-run broker with more than 30 years of experience, we start by asking what you can show and fit the funder and contract to it, rather than sending you to the one with the longest list. We compare contract hire agreements for you, so you see the options before anything is searched.
Our aim is fixed monthly payments, no hidden fees and a process where you know what is coming next. We are FCA authorised and BVRLA members, and if your situation is unusual, such as self-employment, a recent move or a thin credit file, tell us first. It is far easier to plan around it than to explain it afterwards.
Jason
Ready to start your lease?
When your documents are lined up, the next step is a quote. Lease World compares personal and business deals across a wide range of makes and models, with fixed monthly payments, no deposit options and free mainland UK delivery on eligible new vehicles.
Browse personal car leasing, look at electric car leasing, or send us a leasing enquiry and we will tell you exactly what we need from you.
FAQ
What is the minimum I need to apply for a car lease?
You can usually start with an online form containing your personal details, address history, employment and income, and bank details. The funder then verifies these, which is when ID, proof of address and income evidence are requested. Having them ready speeds up the approval.
Can I lease a car without payslips?
Often yes. Lenders may accept bank statements as proof of income, and some use Open Banking with your permission. Affordability checks still apply, so your statements need to show regular income and manageable outgoings.
Do I need a deposit document or proof of savings?
Not normally. Many leases, including our no deposit options, work on an initial rental or no upfront payment at all. The funder is more interested in your income and credit history than your savings.
How old can my proof of address be?
Funders generally want recent documents, typically from the last few months. Ask your adviser what the funder in your case will accept, and use a full statement or bill that shows your name, address and date.
Do I need my driving licence photocard?
You need a valid licence, and the funder will want to verify it. Sharing your record through a GOV.UK check code is the usual way to do this. Keep your licence address up to date with the DVLA.
Sources
- What Proof of Income do you need for Car Finance?
- View or share your driving licence information, GOV.UK
- Best car pre wash for UK owners: 2026 tested guide