
You can usually pass a UK lease eligibility check if you have a full driving licence, proof of address dated within the last 90 days, evidence of income, and a credit record without recent serious defaults. Lenders must run mandatory credit and affordability checks, typically a hard search once you formally apply. Missing a document rarely means rejection outright, but it's worth gathering everything and running a soft check before you commit to a full application.
TL;DR:
- Most UK lenders prioritize address history and document accuracy over credit scores, with up to five years of address continuity often required.
- Soft credit checks can reveal eligibility and weak points without affecting your credit score, helping you improve chances before full application.
- A full lease application typically involves a hard credit search recorded on your file and a decision made within one to two business days.
- Improving your approval odds includes correcting errors on credit reports, reducing credit utilization, and increasing your deposit size for borderline profiles.
- Having all necessary documents ready and responding quickly to follow-up requests can significantly speed up the leasing approval process.
Table of Contents
- Lease eligibility checklist: documents and criteria lenders expect
- How do credit and affordability checks actually work?
- What affects your chances, and how do you improve them before applying?
- How do you prepare and submit a lease application?
- How Lease World supports your eligibility check
- The eligibility question most people are asking wrong
- Get a tailored eligibility check and quote from Lease World
- Sources
- FAQ
Lease eligibility checklist: documents and criteria lenders expect
Every UK lender working with a leasing broker checks the same basics before agreeing to fund a vehicle. Get these ready first and the rest of the process moves far faster.
Identity and driving documents
- A full UK driving licence (provisional licences are rarely accepted for personal leasing)
- A valid passport, often requested alongside your licence as secondary ID
Proof of address
- A utility bill, bank statement, or council tax bill dated within the last 90 days
- A longer address history than you might expect: personal leasing (PCH) can require up to five years of address history, compared with several years for other finance products
Proof of income
- Recent payslips (usually the last three months) for employed applicants
- For self-employed applicants, two years of SA302 tax calculations and a Tax Year Overview from HMRC
- Pension statements or benefit award letters where income comes from these sources
Other requirements
- A UK bank account set up for direct debit payments
- Minimum age of 18, though many lenders prefer applicants to be 21 or older
- A consistent name and address history the lender can verify against credit reference agencies
If you've moved house twice in the last two years or you're newly self-employed, start collecting these documents now. A full breakdown of accepted paperwork is worth checking before you apply, since gaps in address history are one of the most common reasons applications stall.
How do credit and affordability checks actually work?
Every FCA-regulated lender in the UK must assess both your creditworthiness and your ability to afford the repayments before agreeing to a lease. That's not optional; it's a regulatory requirement, not a lender preference.
There are two distinct types of credit search:
- Soft searches compare offers and estimate your acceptance chances without leaving a mark visible to other lenders or affecting your score
- Hard searches happen once you submit a full application, and these are recorded on your credit file
Lenders reviewing your file look for repayment history, missed payments, defaults, County Court Judgments (CCJs), and bankruptcies, alongside the pattern of your existing credit commitments. Affordability checks sit alongside this: your income, your monthly outgoings, and any other repayments all factor into whether the lease payment realistically fits your household budget.
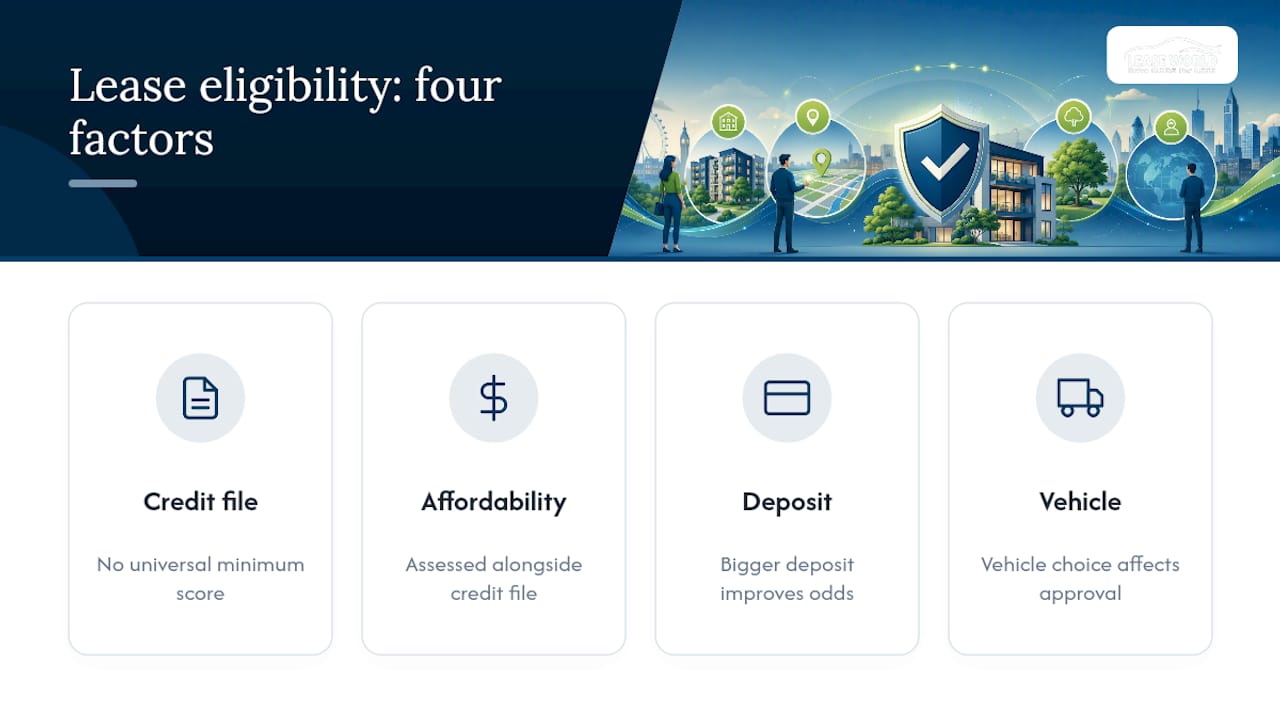
There is no universal credit score that guarantees a lease approval. One lender's rejection is another's acceptance, because appetite varies by funder, deposit size, vehicle choice, and how the affordability numbers stack up overall. A £400 monthly income surplus might comfortably support one lease and fall short for a pricier model with a shorter term.
What affects your chances, and how do you improve them before applying?
Your approval odds depend on a mix of factors you can influence and a few you can't change overnight. Work through these roughly in order:
- Check your credit reports with Experian, Equifax, and TransUnion, and correct any factual errors before you apply. Small mistakes, like an old address still marked as current, can drag your file down unnecessarily.
- Register on the electoral roll if you haven't already. Lenders use it to confirm your identity and address history, and being absent from it is a surprisingly common snag.
- Avoid multiple hard enquiries in a short space of time. Several applications within a few weeks can make you look financially stretched even if each one was reasonable on its own.
- Reduce credit card balances where you can. Utilisation, how much of your available credit you're using, matters more than most people assume.
- Bring a larger deposit if your file is borderline. It lowers the lender's risk and can offset a patchier credit history.
- Tighten your monthly budget before applying, since lower recorded outgoings improve your affordability picture on paper as well as in reality.
If your credit history includes recent major negative markers, a CCJ or bankruptcy within the last year, it's often better to wait and rebuild before applying rather than risk a rejection that leaves another mark on your file.
Pro Tip: If your credit isn't quite where you'd like it, a guarantor arrangement or a specialist subprime funder can still get you into a lease, though expect higher monthly costs to reflect the added risk the lender is taking on.
How do you prepare and submit a lease application?
Once your documents are in order, the actual application process is refreshingly quick.
- Gather your paperwork first: driving licence, proof of address dated within the last 90 days, and proof of income or SA302s if you're self-employed. Doing this before you apply avoids delays later.
- Run a soft eligibility check through a broker or online tool. This estimates your acceptance likelihood without touching your credit score, so there's no downside to checking before committing.
- Submit your full application. This triggers the formal credit and affordability check, and lenders typically return a decision within one to two business days.
- Respond quickly to any follow-up requests. Lenders occasionally ask for an extra payslip or clarification on an address gap. Turning these round fast keeps the process moving toward a signed agreement.
How Lease World supports your eligibility check
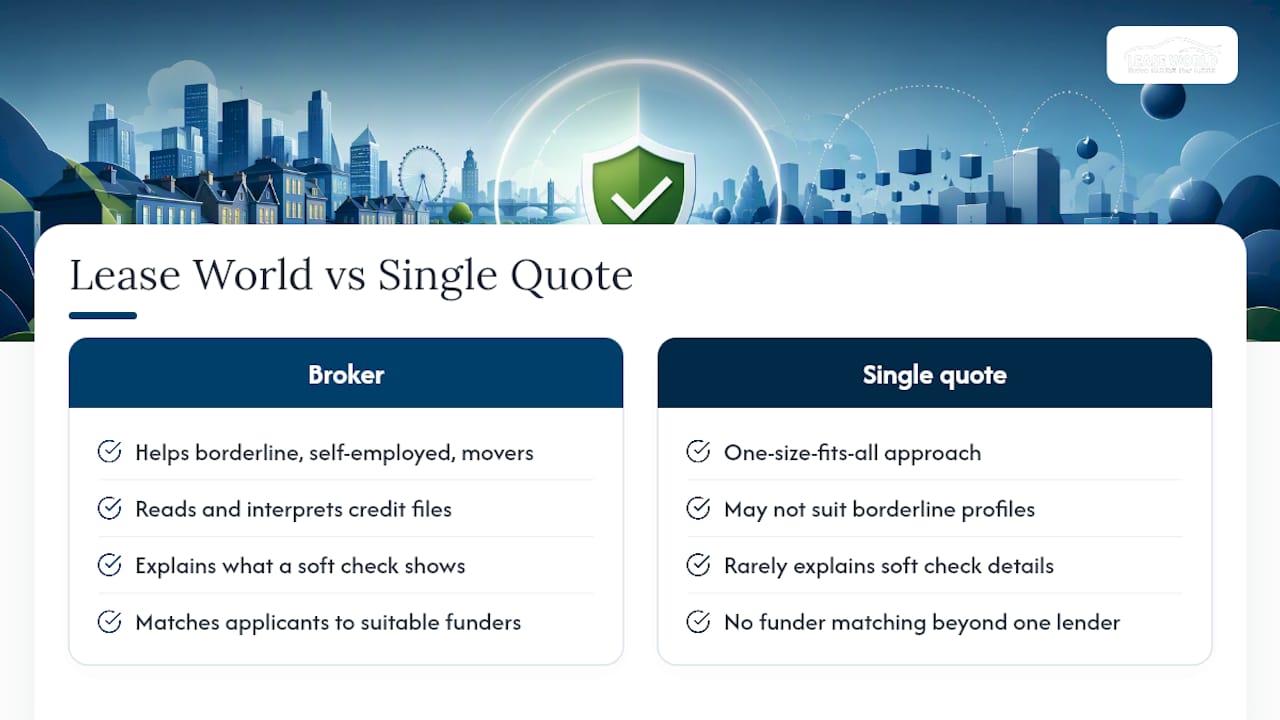
Borderline profiles, self-employed applicants, and anyone juggling multiple address changes benefit most from a broker who can read a credit file properly. Lease World's eligibility guidance explains what a soft check actually reveals and matches applicants to funders whose lending appetite fits their profile, rather than a one-size-fits-all approach.
Some leasing brokers work with transparent pricing, fixed monthly payments, and no-deposit options where eligible, plus complimentary UK delivery on qualifying vehicles. For anyone wanting a tailored contract comparison rather than a single take-it-or-leave-it quote, that kind of hands-on comparison is where a broker earns its keep.
The eligibility question most people are asking wrong
Most guidance on this topic treats eligibility as a pass/fail gate tied to a mythical minimum credit score. That framing is misleading. There's no threshold number that unlocks approval everywhere, because affordability, deposit size, and vehicle choice all move the goalposts as much as your credit file does.
The bigger failure I see in conventional advice is the obsession with credit score while ignoring address history. Personal leasing can demand up to five years of address continuity, and that catches out plenty of otherwise strong applicants who've simply moved twice for work. Sort your documentary trail before you worry about squeezing three extra points out of your credit score.
Prioritise the soft check. It costs you nothing, reveals genuine weak points, and stops you racking up needless hard searches that make lenders nervous about desperation borrowing. Everything else, deposit size, guarantors, timing, is secondary to getting that first honest read on your position.
— Jason
Get a tailored eligibility check and quote from Lease World
Some brokers offer to check your documents, match you to funders suited to your profile, and provide fixed monthly payments with no hidden fees.
Once you've gathered your licence, proof of address, and income evidence from the checklist above, the next step is straightforward. Start with personal car leasing if you're applying as an individual, or head to business car leasing if you're leasing through a company or as a sole trader. In either case, a broker's team may review your circumstances and point you towards funders likely to approve, with complimentary UK delivery on eligible vehicles once the agreement is signed. Ready to see where you stand? Request your personalised quote and get a straight answer on your eligibility.
Sources
- What checks are done for car finance? | Experian
- What documents do I need to lease a car? | The AA
- What documents do I need for car finance? | Carplus FAQ
FAQ
What is the minimum credit score to lease a car in the UK?
There isn't one universal minimum; lenders set their own thresholds and weigh affordability, deposit size, and vehicle choice alongside your credit file. Someone with a modest score can still get approved through a specialist funder or with a larger deposit.
What documents do I need to lease a car?
You'll need a full UK driving licence, proof of address dated within the last 90 days, and proof of income such as payslips or SA302s if you're self-employed. Personal leasing can also require up to several years of address history, rather than just a single recent document.
Does checking my lease eligibility affect my credit score?
A soft eligibility check does not affect your credit score, since it's designed purely for comparison purposes. Only the hard search run at full application stage gets recorded on your credit file.
How long does a lease application decision take?
Most lenders return a decision within one to two business days once you submit a full application. It can take longer if the lender requests additional documents to clarify your income or address history.
What happens if I'm refused a car lease?
A refusal isn't final; you can try a specialist subprime lender, add a guarantor to strengthen your application, or spend a few months improving your credit file before reapplying. Lease World can also review your profile and suggest funders better matched to your circumstances.