
Yes, you can add a named driver to a leased car, but only once your insurer has confirmed cover in writing and any funder restrictions have been cleared. Skipping either step is where drivers get caught out. The immediate action is simple: check your lease agreement first, then contact your insurer or broker for written confirmation before the new driver touches the keys, and sort a VE103 early if you are heading abroad.
TL;DR:
- Adding a named driver to a leased car requires written confirmation from the insurer and approval from the funder before the driver uses the vehicle.
- Lease contracts often contain restrictions on driver age, overseas use, or specific driver categories, which must be checked and documented before adding a driver.
- Changes in a driver's license status, such as upgrading from provisional to full, can affect insurance premiums, but no-claims discounts usually do not transfer automatically.
- If traveling abroad, customers must obtain a VE103 certificate and get approval from both insurer and funder well in advance of the trip.
- Disputes related to driver points or claims are best avoided by truthful declaration, as misreporting can lead to policy voidance and potential fraud allegations.
Table of Contents
- Who can drive a leased car: lessee, named driver and registered keeper
- How do I add a named driver to a lease car?
- Will adding a driver change your lease car insurance cost?
- Does your lease agreement restrict who can drive the car?
- Learner drivers and telematics: what changes
- Taking a leased car abroad: do you need a VE103?
- What happens if a named driver gets points or has an accident?
- How Lease World supports customers adding a named driver
- What one habit prevents most named-driver problems?
- Get help adding a named driver to your lease
- Sources
- FAQ
Who can drive a leased car: lessee, named driver and registered keeper
Three roles get muddled constantly, and the confusion causes real problems. The lessee is the person who signed the lease agreement with the funder and is contractually responsible for the vehicle. The named driver is purely an insurance status: someone added to the policy who is legally permitted to drive that car. The registered keeper is whoever the vehicle is registered to with the DVLA, which on a lease is often the funder, not you.
Being a named driver does not make someone a party to the lease or give them any ownership stake. It is an insurance arrangement only, so lease terms and insurance rules run separately and both need checking.
Most funders permit additional insured drivers, but watch for these limits:
- Minimum age thresholds, often 21 or 25 depending on the funder
- Licence-type restrictions (some funders exclude provisional licences entirely)
- Business-use exclusions if the car is only insured for social, domestic and pleasure use
- Restrictions tied to specific driver categories, such as couriers or instructors
How do I add a named driver to a lease car?
Getting the order right matters more than most drivers assume. Follow these steps before anyone new gets behind the wheel.
- Read the lease contract for driver clauses. Some agreements restrict who else may drive the car or place limits on overseas use, separate from anything your insurer requires.
- Gather the named driver's full details. Insurers typically want full name, date of birth, address, licence number and type, occupation, motoring history, and any convictions or endorsements, plus how the car will actually be used.
- Contact the insurer or broker before the person drives. Ask for an updated policy schedule and a clear effective date, in writing, not a verbal assurance over the phone.
- Pay any revised premium or admin fee and keep the confirmation. Check what happens at renewal too, since some insurers reassess the whole policy once a new driver appears on it.
- Request funder permission and a VE103 early if travel abroad is planned. Both approvals can take longer than drivers expect, so start well before departure.
Pro Tip: Save the insurer's written confirmation as a PDF or screenshot with a timestamp. If a dispute ever arises after an accident, that single document is usually what settles it.
Will adding a driver change your lease car insurance cost?
There is no fixed rule here, and that surprises a lot of drivers expecting a straight increase. Adding a named driver can push the premium up, bring it down, or leave it untouched entirely, depending on how the underwriter assesses the new driver's risk profile against the existing policy.
A few effects come up repeatedly in practice:
- Licence-status changes matter. Moving from a provisional to a full licence, Saga's guidance notes, often triggers a premium reassessment, so disclose the change promptly rather than waiting for renewal.
- No-claims discounts rarely transfer automatically. A named driver usually cannot claim the policyholder's no-claims history as their own; check the insurer's specific terms rather than assuming it carries over.
- Telematics devices track everyone who drives the car. If your policy uses a black box, ABI's consumer guide on telematics confirms the data usually aggregates across all drivers, meaning a named driver's habits behind the wheel can affect your own score and discount.
None of this is guesswork you need to do alone. A quick call to your insurer with the named driver's details will tell you the actual number before anyone commits to anything.
Does your lease agreement restrict who can drive the car?
Insurance cover and funder permission are two separate hurdles, and clearing one does not clear the other. Lease contracts frequently include their own clauses on additional drivers, age limits, or taking the vehicle outside the UK, entirely independent of what your insurer allows.
Before letting anyone else drive, check and document the following:
- Whether your lease agreement names any restrictions on additional drivers or minimum ages
- Whether cross-border travel needs separate funder sign-off, and whether a VE103 is required from the AA, RAC, or BVRLA
- Written proof of both funder consent and insurer confirmation, kept together in case a claim or vehicle return raises questions later
Skipping the paper trail is the single most common reason disputes escalate at the point a car is handed back or a claim is lodged.
Learner drivers and telematics: what changes
Learner drivers need explicit cover before they touch a leased car. GOV.UK's guidance on supervising learners confirms they must either be added as named drivers with provisional cover or hold their own learner policy, and some insurers require the supervising adult to be over 25.
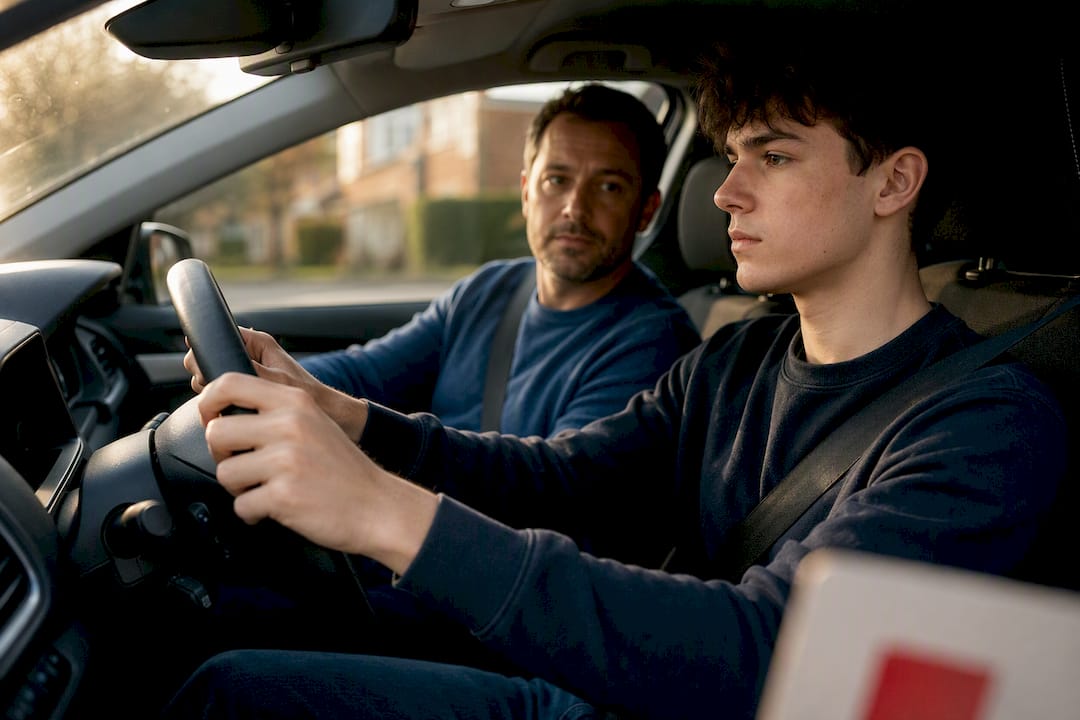
Driving instruction and courier work both need business-use cover, since ordinary social, domestic and pleasure policies typically exclude professional instruction entirely. If you are arranging lessons in a leased car, a service like Connect Driving School can advise on the supervision and instructor arrangements that fit alongside your policy.
If your policy runs telematics, confirm how an added driver's data feeds into your dashboard and discount before they start driving.
- Ask whether the black box separates driver behaviour or lumps it together
- Check whether a learner's driving style could dent your telematics score
Pro Tip: Tell your insurer about a learner before the first lesson, not after. Retrospective disclosure is far more likely to trigger awkward questions than a five-minute call beforehand.
Taking a leased car abroad: do you need a VE103?
A VE103 certificate proves you have permission to take a hired or leased vehicle outside the UK, and you need it sorted before you travel, not at the ferry port. It is issued through organisations such as the AA, RAC, or BVRLA, and there is usually a fee attached.
Tell both your funder and insurer about the trip well in advance. Some funders restrict which countries you can visit, and some insurers apply different cover terms once you cross the Channel.
- Request the VE103 and insurer confirmation together, ideally weeks ahead of departure
- Keep both documents as physical or digital copies with you on the trip, alongside proof of your insurance for the leased vehicle
What happens if a named driver gets points or has an accident?
Points and claims attach to the individual driver involved, and they must be disclosed to the insurer. That record can push up the premium at renewal or prompt the insurer to reassess the whole policy, sometimes for every driver named on it, not just the one at fault.
Never declare someone other than the true main driver just to lower the price. The ABI is explicit that fronting is fraud, and misdeclaring the main user can void cover entirely at the worst possible moment, during a claim.
- If your insurer refuses to add a driver or rejects a claim, start with the insurer's formal complaints process first
- If the dispute stays unresolved, the Financial Ombudsman Service has ruled on cases involving inaccurate main-driver declarations, and it remains the next step when an insurer's answer does not satisfy you
How Lease World supports customers adding a named driver
Getting a named driver onto a lease car correctly involves a lot of small, easily missed steps, which is exactly where a broker earns its keep. A family-run leasing business can work through a consistent process with customers: reviewing the lease contract for driver clauses, liaising with the insurer to confirm what they need, chasing written confirmation before anyone drives, and helping arrange VE103 paperwork when travel abroad is planned.
That process runs alongside practical basics such as fixed monthly payments, no deposit options on eligible agreements, and free UK delivery on eligible vehicles. Every confirmation obtained on a customer's behalf gets kept on file, so if a question comes up months later at renewal or handback, there is a paper trail rather than a guess.
- Contract review before any driver change is agreed
- Direct insurer liaison to confirm terms in writing
- VE103 support for customers planning trips abroad
- Records kept so nothing relies on memory
What one habit prevents most named-driver problems?
The pitfalls repeat themselves: drivers act on a verbal promise from an insurer, skip the lease small print entirely, or forget to update cover when circumstances shift. The single habit that heads off nearly all of it is boring but effective. Get written confirmation from both your insurer and your funder before anyone new drives the car, and keep it somewhere you can find it again.
— Jason
Get help adding a named driver to your lease
Some drivers work through the insurer and funder calls themselves, and that is entirely doable with the checklist above. But if you would rather have someone chase the confirmations, check the contract clauses, and sort the VE103 paperwork on your behalf, that is exactly the gap Lease World fills for customers already leasing through them.
A leasing team can review lease terms and liaise with insurers as part of ongoing customer support, alongside fixed monthly payments and no deposit options that some leasing services offer. If you are still shopping for a lease and want a provider that handles these questions from day one rather than leaving you to work them out later, browse personal car leasing deals or request a quote to talk through your situation directly.
Sources
- Gov
- Named driver insurance: does adding a named driver reduce my insurance? - RAC
- Motor insurance - ABI guidance
FAQ
Can my wife drive my lease car?
Yes, provided she is added as a named driver on your insurance policy and your insurer has confirmed cover in writing. Check your lease agreement too, since some funders set their own conditions on additional drivers separate from the insurance side.
What is the 1.5 rule when leasing a car?
This is not a recognised industry or legal term in UK vehicle leasing, and no such rule appears in GOV.UK or ABI guidance. If you have seen it mentioned elsewhere, it likely refers to a specific lender's internal policy rather than a general market standard, so check directly with the funder in question.
Can you insure a leased car not in my name?
Usually not as the policyholder, since most insurers expect the person taking out the policy to be the lessee or a close named driver, but arrangements vary by insurer. It is worth reading how insurance responsibilities differ on a leased car before assuming either way.
Can my mum lease a car for me?
She could sign the lease agreement as the lessee, but that does not automatically mean you are covered to drive it. You would still need to be added as a named driver on the insurance policy, with the insurer's written confirmation in place before you get behind the wheel.